Money problems are one of the most common sources of tension in Canadian relationships. A 2024 RBC poll found that 77% of couples say money is a source of stress, and 62% said money caused arguments (1). The problem isn’t only about numbers on paper — it’s about values, habits and trust.
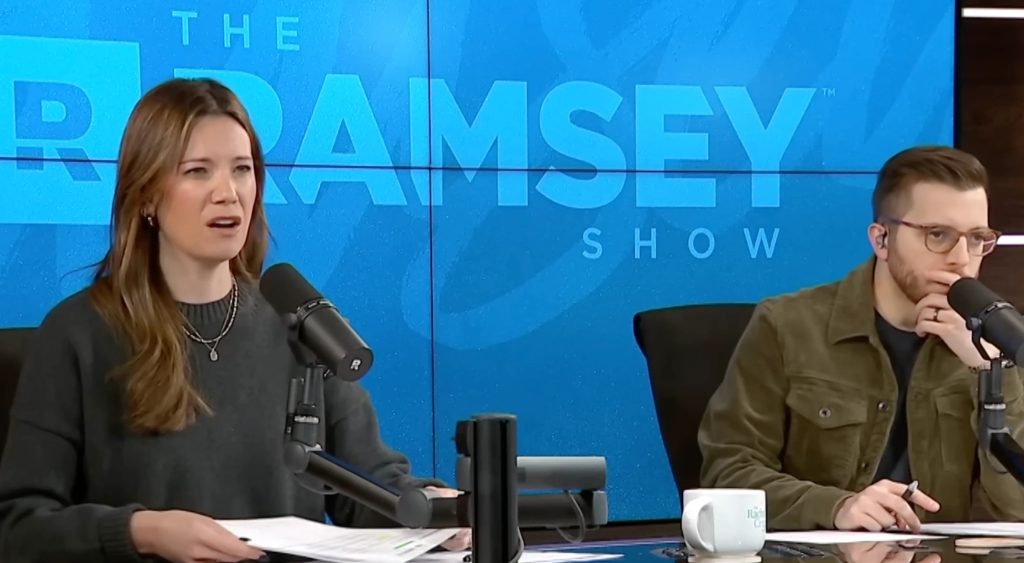
Rita, a caller on The Ramsey Show, reached out to hosts Rachel Cruze and George Kamel after her fiancé called off their engagement when he found out about the extent of her debt and spending habits (2). Her story offers a candid look at what happens when financial incompatibility reaches a breaking point — and what to do when it does.
Don’t Miss
- A single line on your car insurance policy could be inflating your premium by up to 30% — here’s what to change
- Here are 5 ‘must-haves’ that Canadians constantly overpay for. How many of these are sabotaging your budget every single month?
- Dave Ramsey says this 1 indulgent purchase stops people from becoming wealthy. Here’s what he recommends instead
‘Money can become such an identity marker in us’
Rita told Cruze and Kamel that after her father passed away — when she was just 19 years old — she took on significant financial responsibility for her younger siblings. That burden, layered on top of student debt, left her in a difficult financial position. She’s still navigating a situation where her finances are closely tied to her sister and her semi-retired mother.
"Money is very emotional for me, because I don’t have a good relationship with it, and my family doesn’t. So when it came time to start going through the finances, it didn’t go well," she said.
Cruze and Kamel acknowledged the hurt Rita was feeling, but challenged her to rethink how she sees herself in relation to money.
"He broke up with the most vulnerable part of you," Cruze told her. "Money can become such an identity marker in us, and it shouldn’t be. Your money mistakes, your net worth, none of this is who you are as a person."
Kamel pushed her to use the breakup as a turning point: "You asked, ‘How do I heal?’ Well, learn from what broke, and rebuild trust in yourself. Then create the habits and become the person that you want to be. The person who changes your family tree and actually gets out of debt. This just might be one of those forks in the road where you look back and go, ‘Man, that was a pivotal time in my life.’"
Ready to become debt-free? Use the Money.ca comparison tool to see how much you could save by moving your high-interest balance to a low-rate card today.
Read more: 3 essential money moves to make once you’ve saved $50,000
Money, identity and relationships in Canada
Rita’s experience reflects a larger pattern. In Canada, household debt is a significant and growing issue. Statistics Canada data shows that for every dollar of disposable income, Canadian households carry approximately $1.77 in debt (3). That kind of financial pressure can’t be separated from a serious relationship.
Separating a person’s identity from their money mistakes — the way Cruze and Kamel advised Rita to do — is useful for couples trying to navigate different financial backgrounds and habits. It doesn’t mean excusing genuinely harmful financial behaviour: red flags like problem gambling, compulsive spending or financial dishonesty are serious concerns in any relationship.
But a partner who’s carrying debt from a difficult period in their life, and who is actively working to address it, is a different story. Instead, Cruze and Kamel advised a mindset shift from "I’m bad with money" to "I’ve made money mistakes I can fix" as the foundation for anyone in Rita’s position to start from.
Financial compatibility: What it looks like
Financial compatibility doesn’t mean two people have identical bank balances or spending habits. Instead, it includes:
- A willingness to talk openly about money, debts and financial goals
- Similar or complementary savings habits and attitudes about investing
- A shared approach to managing or paying down debt
- Aligned goals around major financial milestones — homeownership, retirement savings, emergency funds
- Honesty and consistency, even when the picture isn’t flattering
These conversations don’t happen all at once, and they don’t need to. What matters is that they happen at all — and that both partners are willing to keep having them as circumstances change.
Marriage and debt in Canada: What you need to know
One important point for Canadians: if Rita and her fiancé had married, he wouldn’t automatically be legally responsible for her premarital debts. In Canada, debt incurred before marriage generally remains the sole liability of the person who took it on. Under provincial family property legislation, only debts taken on during the marriage are subject to sharing between partners in the event of a separation, and even then, the rules vary by province and by the nature of the debt (4). Pre-marital student loans, for example, wouldn’t become a shared debt simply by getting married.
That said, a partner’s debt load can still affect a couple’s financial life in practical ways. If one partner carries significant debt — particularly high-interest consumer debt — it can drag down their credit score. In Canada, credit scores are calculated by Equifax and TransUnion on a scale of 300 to 900, with scores above 660 generally considered "good" (5). A low credit score can affect a couple’s ability to qualify for a mortgage, secure a car loan or get competitive interest rates on joint credit products.
Getting your finances ready for a serious commitment
If you’re in Rita’s position — carrying debt into a relationship and wanting to get your finances in order — the steps are straightforward, if not always easy:
- Build a realistic budget based on your real spending, not how you wish you spent.
- Choose a debt repayment strategy that works for you. For example, the snowball method involves paying smallest debts first for psychological wins, versus the avalanche method, which pays highest-interest debts first to save the most money.
- Consider reaching out to a non-profit credit counsellor. The Credit Counselling Society (CCS) offers free or low-cost services across Canada.
- Explore a debt consolidation loan through your bank or credit union to simplify payments and potentially lower your interest rate.
- Once high-interest debt is under control, build an emergency fund of at least three to six months of living expenses.
- Start contributing to a Registered Retirement Savings Plan (RRSP) or a Tax-Free Savings Account (TFSA), even in small amounts, to build long-term financial security.
Be honest with your partner about where you are in this process, and keep them updated on your progress. Financial transparency is one of the strongest foundations you can build a relationship on.
When your partner’s finances are a dealbreaker
Rita’s fiancé made the decision to walk away. That is a deeply personal choice, and not always the wrong one. A partner who makes promises about changing their financial habits but doesn’t follow through may not be ready for a serious financial commitment. Some red flags include:
- Accumulating more debt rather than reducing it
- Hiding spending, debts or financial obligations from you
- Gambling or making high-risk financial decisions without discussion
- Refusing to talk about money or dismissing your financial concerns
Protecting your own financial health isn’t selfish — it’s a form of care for your shared future.
Canadian next steps: Turning your financial story around
If Rita’s story resonated with you, here are concrete steps you can take:
- Contact the Credit Counselling Society at creditcounsellingbc.ca (6) or 888-527-8999 toll-free for confidential debt advice
- Use the Financial Consumer Agency of Canada’s (FCAC) Budget Planner tool at fcac-acfc.gc.ca/BP-PB/budget-planner (7) to map your income and expenses
- Request your credit report for free from Equifax and TransUnion to understand your credit standing
- Talk to your bank about a debt consolidation loan or line of credit to roll high-interest debts into a single, lower-rate payment
- Open or maximize contributions to a TFSA — contributions grow tax-free and can be withdrawn at any time without penalty
- If you have earned income, contribute to an RRSP to reduce your taxable income today and build retirement savings for tomorrow
- If your financial situation involves a spouse or common-law partner, speak with a licensed financial planner about how to structure your money in a way that protects both parties
Debt isn’t a permanent identity — it’s a problem with a solution. The key, as The Ramsey Show‘s hosts told Rita, is to stop seeing yourself as someone who is "bad with money" and start making the choices that show you who you actually want to be.
-With files from Melanie Huddart
What To Read Next
- Here are the 5 biggest differences between rich and poor Canadians — which side do you fall on?
- This 7-step plan from Dave Ramsey is designed to help you ditch debt, save more and build wealth — here’s how it works
- Need to stretch your dollars this month? Copy these 7 shopping habits that are actually saving Canadians money
- Gold still crashing!’: Robert Kiyosaki admits he was wrong — but doubles down on his $35K prediction
Join 19,000+ readers and get Money.ca’s best stories and exclusive interviews first — clear insights curated and delivered weekly. Subscribe now.
Article Sources
We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.
CIBC (1); YouTube (2); The Globe and Mail (3); Canada Life (4); Credit Card Genius (5); Credit Counselling Society (6); Financial Consumer Agency of Canada (7)
This article provides information only and should not be construed as advice. It is provided without warranty of any kind.